Beverage August 2, 2026 ECGO Research Team
Where Gen Z's Brand Loyalty Is Actually Legible
Gen Z is supposedly rotating through every brand on the shelf. Yet in ECGO's June panel, beverage reach stays remarkably consolidated while other categories fragment — and that gap tells you exactly where you can build a plan.
Product & Brand Performance
The drumbeat in beverage research lately is that Gen Z's "go-to drink" is dead — younger consumers now rotate across more flavors, functions, and categories than any generation before them, with a large majority saying they want function-forward drinks. If everyone's rotating, you'd expect brand reach to scatter. In ECGO's June panel, it doesn't — at least not everywhere.
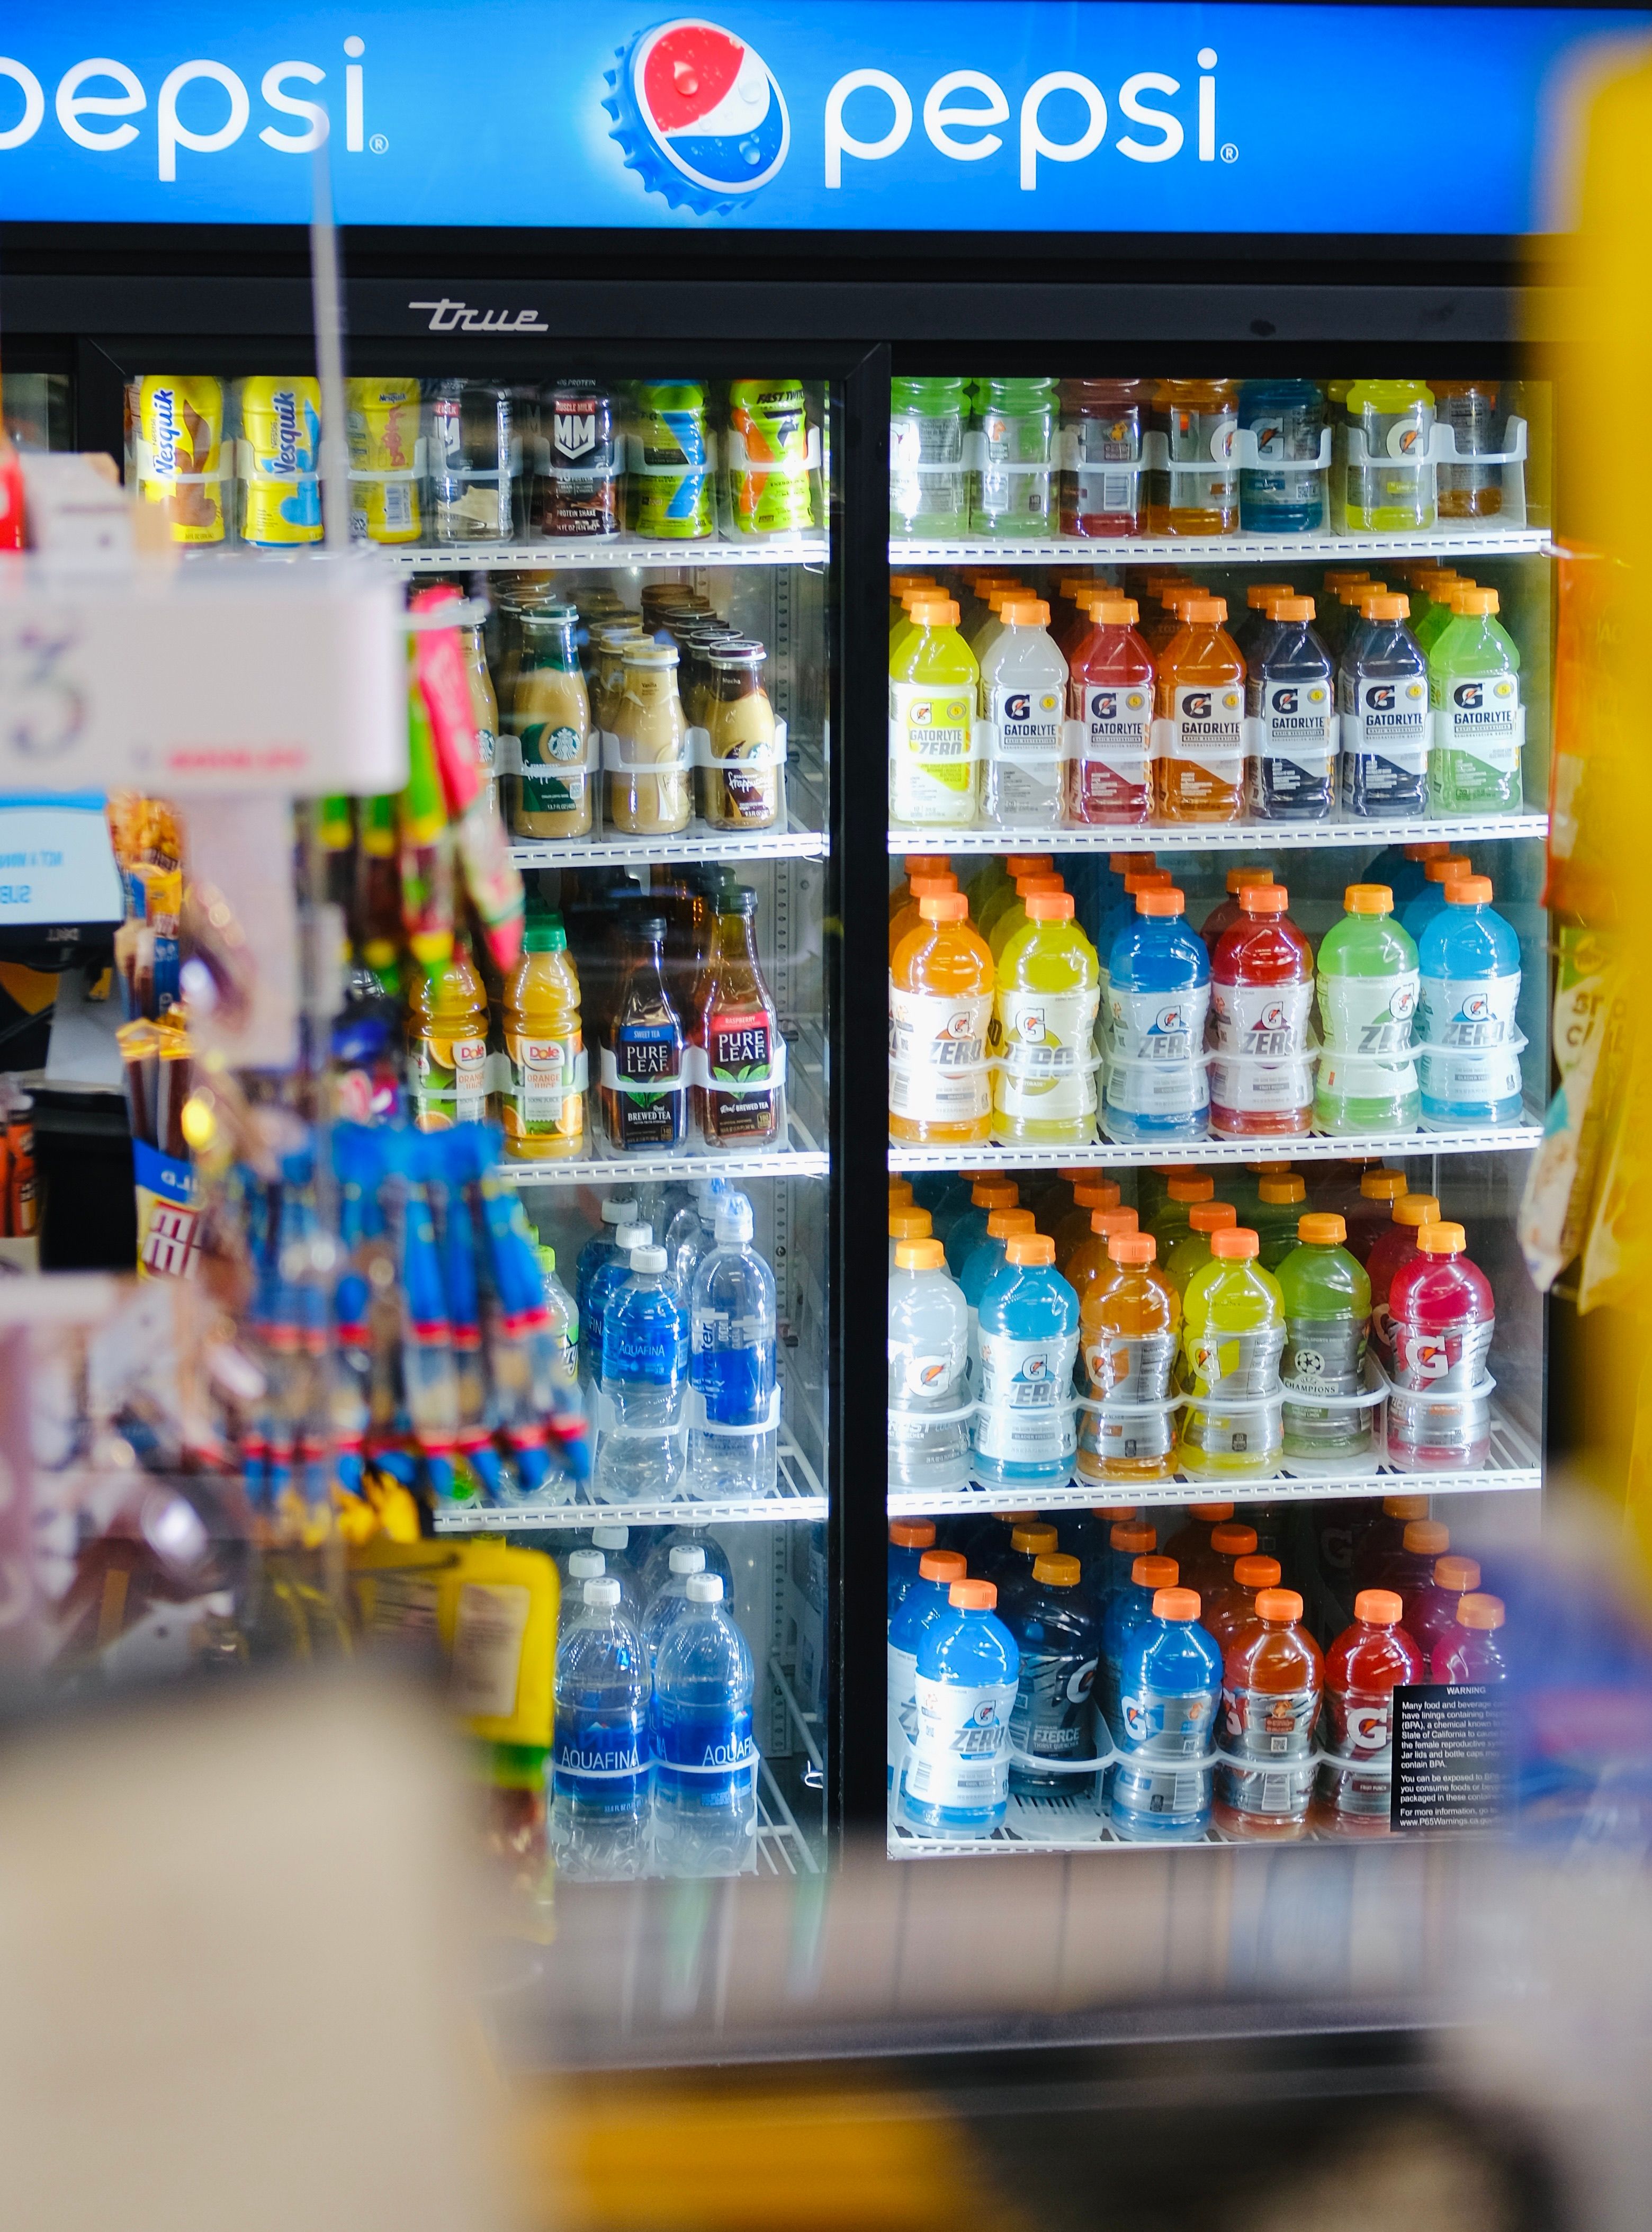
Beverage reached 74% of the panel this edition, miles ahead of Food (43%) and Personal Care (37%). But the more useful signal is inside the aisle. Two brands — Gatorade and Kirkland's water line — each landed in 15% of the panel's baskets. At this panel size, 15–20% is effectively the top of the scale, so that's not a modest showing; it's consolidated reach. Gatorade's users also come back on a tight cycle, roughly every ten days.
Step outside beverage and that concentration vanishes. The most-reached snack and dairy brands top out around 2–4% of the panel — plenty of category energy, but no single brand owning the shelf.
Here's why that matters for a category team. Beverage is the one category this edition where Gen Z brand preference is legible enough to build a plan around — where you can name the winners and see how often they're chosen. In Food and Personal Care, the honest read right now is category-level, not brand-level. That's not a weakness in the data; it's a map of where brand equity is concentrated versus where the field is still wide open.
The full portfolio and sub-category breakdown ranks every tracked brand on reach and repeat cadence. That's where the rest of this lives.